Impact-Resistant roofs and insurance discounts: What to know before you buy
Last updated · Storm damage & insurance
Short answer: Many insurers in hail-prone states offer a premium credit for roofs rated to resist impact, usually UL 2218 Class 4. Discounts vary by company, state, and policy, and some states require insurers to offer them. Call your agent before you buy to ask what credit applies and what proof they need. No product is hail-proof.[1]
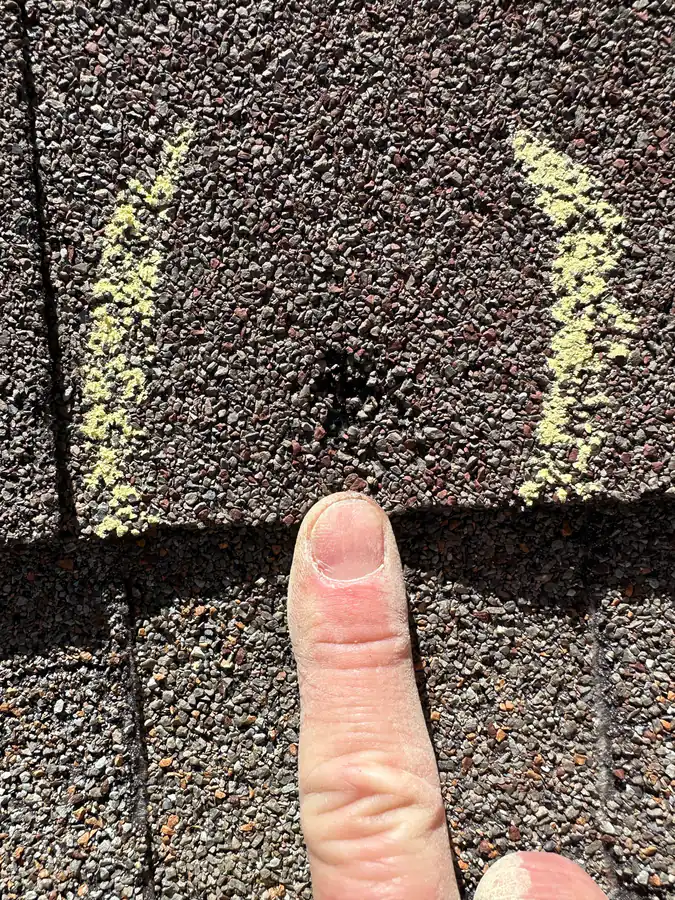
What makes a roof impact-resistant?
A roof is called impact-resistant when its roofing product has passed a standard impact test. The most common is UL 2218, which drops steel balls of increasing size onto the product; Class 4 is the top rating. A newer test, FM 4473, uses ice balls fired at the product. These ratings are printed on the product packaging and listed by the manufacturer. The Texas Department of Insurance keeps a list of products that qualify for impact-resistant roofing credits in Texas.[1]
Do all Class 4 shingles perform the same?
Not all Class 4 shingles perform the same in real hail. The Insurance Institute for Business & Home Safety tested impact-resistant shingles with realistic hailstones and published ratings showing wide differences between products that share the same Class 4 label.[2] Some held up well, while others cracked or lost granules more easily. If hail is your main concern, look at the IBHS ratings along with the UL class.
Which states have impact-resistant roof discounts?
Several hail-prone states have rules or programs tied to impact-resistant roofs. Texas requires insurers that offer credits to recognize qualifying products and publishes the eligible list.[1] Alabama's Department of Insurance publishes a chart of discounts insurers offer for homes built or retrofitted to the FORTIFIED standard, which includes impact and wind features.[3] Other states, such as Oklahoma, Kansas, and Colorado, have insurers that offer credits by company choice. Rules change, so ask your agent or state insurance department.
How much of a discount can you expect?
How much of a discount you can expect depends entirely on your insurer, state, and policy. Some companies offer meaningful credits on the wind and hail part of the premium; others offer little or none. Ask your agent for the exact credit in dollars on your current policy before you choose a roof. That number, compared with the extra cost of the impact-rated product, tells you how long the upgrade takes to pay back.
What proof do insurers ask for?
Insurers usually ask for proof that the roof qualifies. Common documents are: - The final invoice naming the product and its impact rating - A copy of the product packaging label or manufacturer data sheet - A certificate or form signed by the roofer, if your state uses one - For FORTIFIED, the designation certificate from IBHS Keep these in one folder and send them to your agent right after the roof is finished.
What is a FORTIFIED Roof?
A FORTIFIED Roof is a designation from IBHS for roofs built to a set of standards that go beyond typical code, including a sealed roof deck, enhanced deck nailing, and stronger edge details.[4] In hail areas, it can include impact-rated shingles. A third-party evaluator checks the work during installation. Some states, including Alabama, link insurance discounts or grants to FORTIFIED designation.
Are there downsides to impact-resistant roofs?
There are a few downsides to impact-resistant roofs. They usually cost more than standard shingles. Some policies use cosmetic-damage exclusions, which can limit claims for dents or marks that do not cause leaks, and those exclusions may apply to impact-rated roofs. Read your policy and ask your agent how cosmetic damage is handled. Only your insurer decides what a policy covers.
How do you decide if an impact-resistant roof is worth it?
To decide whether an impact-resistant roof is worth it, compare the added cost with your expected discount and your hail risk. If you live where large hail is common, the added durability may matter more than the discount. Check the IBHS ratings, get the discount amount in writing from your agent, and ask your roofer to quote both standard and impact-rated options so you can compare.
Rather talk to someone? Request a callback
Leave your name and number and a local roofing contractor will call you back about a free estimate and inspection. Available to homeowners in our service markets.
- A local contractor calls you. They confirm your address and a time that works.
- They inspect your roof. Free, in person, no obligation.
- You get a written price. You decide. No pressure.
Frequently asked questions
Will an impact-resistant roof lower my insurance?
It may, depending on your insurer and state. Ask your agent for the exact credit before you buy.
Are Class 4 shingles hail-proof?
No. They resist impact better in testing, but very large hail can still damage them, and products vary.
What paperwork do I need for the discount?
Usually the invoice naming the product and rating, plus any state form or certificate your insurer requires.
See 2026 roof replacement cost in your city →
Sources
- TDI: Products qualifying for impact-resistant roofing credits. www.tdi.texas.gov/company/roofing-discounts.html
- IBHS, 2025 Impact-Resistant Shingle Ratings release (Nov 19, 2025). ibhs.org/ibhs-news-releases/ibhs-releases-its-most-expansive-impact-resistant-sh
- Alabama Department of Insurance: FORTIFIED Insurance Discount Chart (PDF). aldoi.gov/SAH/Documents/FORTIFIED%20Insurance%20Discount%20Chart.pdf
- IBHS: FORTIFIED Roof Endorsements. fortifiedhome.org/fortified-roof-endorsements/
Sources checked November 4, 2026. Estimates are not quotes. Roofing, insurance, and legal details vary. Confirm with your contractor, insurer, or attorney.